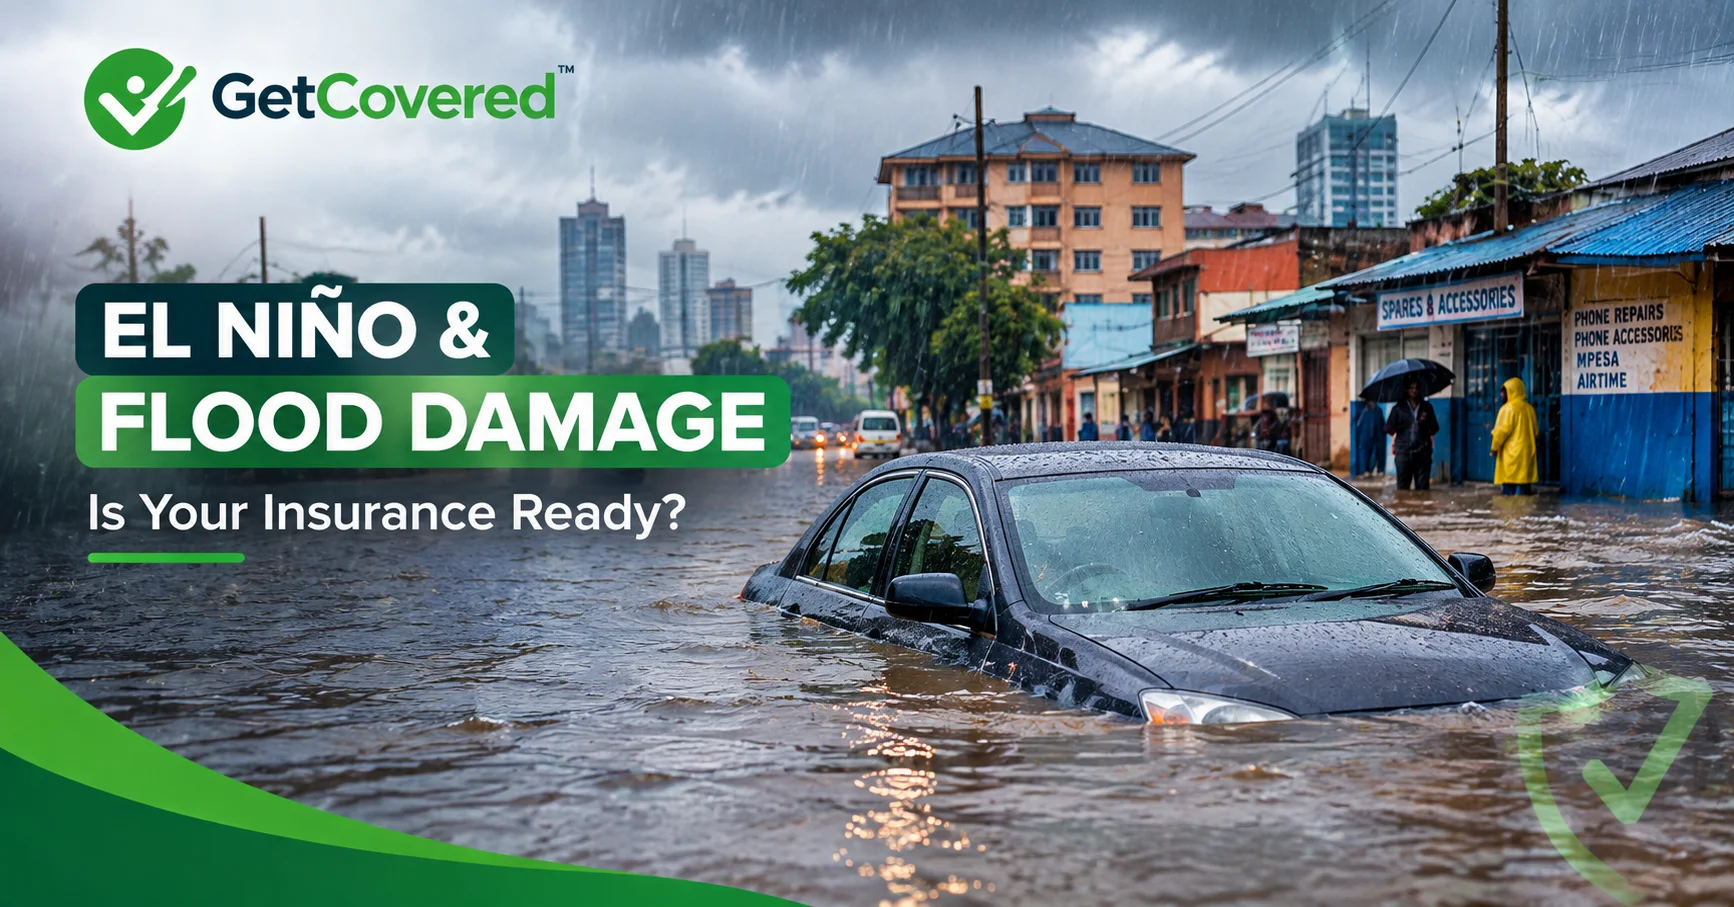
El Niño and Insurance in Kenya: What Happens If the Rains Damage Your Car, Home or Business?
You wake up at 5 a.m. because of the rain.
It has been raining for hours.
You look outside and the road is already starting to fill with water. Your car is parked outside. The drainage near your house is struggling. If you own a shop or business, you are probably wondering whether the premises will be accessible in the morning and whether your stock is safe.
For some Kenyans, heavy rain is simply an inconvenience.
For others, it can become an expensive problem very quickly.
A flooded car can mean a large repair bill. Water entering a house can damage furniture, electronics and other belongings. Flooding around a business can destroy stock, damage equipment and prevent customers from reaching the premises.
And this is why the 2026 El Niño season is worth taking seriously.
According to the latest regional outlook from the IGAD Climate Prediction and Applications Centre (ICPAC), El Niño has developed and is expected to strengthen during the remainder of 2026. The October–December 2026 season is expected to have an increased likelihood of wetter-than-normal conditions across much of the Greater Horn of Africa, including parts of Kenya.
That does not mean that every part of Kenya will flood or that every household will experience property damage.
But it does raise an important question:
If heavy rain or flooding damages something you own, can you afford to pay for everything yourself?
That is where insurance comes in.
What is happening with El Niño in Kenya?
El Niño is a climate phenomenon associated with unusually warm sea-surface temperatures in the central and eastern tropical Pacific Ocean. Its effects can influence weather patterns far beyond the Pacific.
For Kenya, the important issue right now is not the technical definition of El Niño. It is what the current forecasts mean for the coming rainy season.
ICPAC's October–December 2026 outlook indicates an increased likelihood of wetter-than-normal conditions across the Greater Horn of Africa. Its downscaled forecast gives a 90% chance of enhanced rainfall over parts of north-eastern Kenya, while central Kenya and the Lake Victoria Basin are among areas where seasonal rainfall could exceed 400 mm.
Other analysis of the 2026 season has also identified an elevated risk of flooding in parts of Kenya, particularly in areas that are historically vulnerable to heavy rainfall and river flooding.
The important thing to understand is that a seasonal forecast is not a prediction that your particular home, road or car will flood.
Weather conditions can vary significantly from one county, neighbourhood and day to another.
But if you already live or operate in an area where drainage is poor, roads flood easily, rivers overflow or heavy rainfall regularly causes disruption, this is a sensible time to review your risks.
What damage can El Niño rains cause in Kenya?
When people talk about “El Niño damage”, they are usually talking about the consequences of unusually heavy rainfall and flooding.
The damage can affect much more than houses.
Heavy rain and flooding can potentially affect:
- Cars and motorcycles
- Homes and household contents
- Shops and business premises
- Stock and inventory
- Machinery and equipment
- Roads and access routes
- Goods being transported
- Agricultural property and produce
- Business operations and income
For an individual, the financial impact might be the cost of repairing a flooded vehicle.
For a business, it could be much larger.
Imagine a shop with KSh 2 million worth of stock.
The building survives the rain.
The shelves survive.
The business owner survives.
But several inches of floodwater enter the premises and destroy a large portion of the stock.
The problem is no longer simply “bad weather”.
It is a financial loss.
Your car could be one of your biggest El Niño risks
Think about the places where you normally park your car.
Outside your house.
At your apartment.
At work.
At the shopping centre.
Along the road.
Now imagine that the drainage system in that area cannot handle several hours of heavy rainfall.
Water starts accumulating.
You have somewhere you need to be, so you try to drive through it.
That is where a bad situation can become a very expensive one.
Floodwater can damage a vehicle's:
- Engine
- Electrical systems
- Sensors and electronics
- Interior
- Transmission
- Bodywork
- Air-conditioning system
- Wiring
- Other mechanical components
And in severe cases, a vehicle can be damaged beyond economical repair.
Does comprehensive car insurance cover flood damage?
It can, depending on the policy.
This is an important distinction.
Comprehensive motor insurance generally provides broader protection for your own vehicle than third-party insurance, but the exact risks covered depend on the policy wording, exclusions, limits, excesses and extensions.
GetCovered's motor insurance guidance identifies flood and storm damage as risks that may be covered under comprehensive motor insurance, while also stressing that the exact scope depends on the individual policy.
Third-party insurance is different.
It is primarily designed to cover specified liabilities to other people rather than damage to your own vehicle.
So if you are worried about losing your vehicle to flooding during a heavy rainy season, don't simply look at the cheapest motor insurance premium.
Look at what the policy actually covers.
[Internal link: Comprehensive Car Insurance Kenya]
[Internal link: Compare Car Insurance Quotes Kenya]
What about your house?
Your home is another place where heavy rain can become financially painful.
Water can enter through:
- Roofs
- Windows
- Doors
- Walls
- Poor drainage
- Flooded compounds
- Damaged plumbing or drainage systems
The resulting damage may affect furniture, electronics, appliances, fittings and other belongings.
And sometimes the problem is not a dramatic flood.
It might simply be days of heavy rain exposing a leaking roof that you had been postponing.
That small leak can become a much bigger repair bill.
Does home insurance cover flood damage?
The answer depends on the particular policy.
Home and property insurance can provide protection against specified risks affecting buildings and/or their contents, but you should never assume that every policy covers every form of water or flood damage.
Before buying a policy, ask specifically:
- Is flooding covered?
- Is storm damage covered?
- Are household contents covered?
- What is the sum insured?
- What exclusions apply?
- Is there an excess?
- Are there specific conditions I need to meet?
Kenya's insurance regulations recognise domestic fire insurance business that can include house owners, householders and other comprehensive package covers, while property-related insurance can be structured around particular insured risks.
The lesson is simple:
Don't buy “home insurance” based only on the name of the product. Understand the risks actually covered.
Your business may have even more to lose
This is where El Niño risk becomes particularly important for Kenyan businesses.
Consider a small electronics shop.
Or a supermarket.
Or a hardware store.
Or a pharmacy.
Or a wholesaler.
Or an online business storing imported stock in a warehouse.
If floodwater enters the premises, the building itself may not be the biggest loss.
The stock could be.
And even if the stock survives, the business may still be unable to operate.
Customers may not be able to reach the premises.
Employees may not be able to get to work.
Deliveries may be delayed.
Equipment may be damaged.
Electricity may be disrupted.
The business could lose income while repairs are being carried out.
This is why business owners should think beyond:
“Is my building insured?”
A better question is:
“What happens to my business financially if I cannot operate for several days or weeks?”
Depending on the business and policy structure, relevant insurance may include commercial property, stock, business interruption and other covers.
What about goods being transported during heavy rains?
Kenya's businesses do not operate from one location.
Goods are constantly moving between:
- Ports
- Warehouses
- Shops
- Distribution centres
- Farms
- Factories
- Customers
Heavy rain and flooding can disrupt roads and transport routes.
That creates another risk for businesses:
What happens if goods are damaged while they are being transported?
If your business regularly imports or transports valuable goods, you should understand whether your existing insurance arrangements address goods in transit and under what circumstances.
Do not assume that because the goods are insured at your warehouse, they are automatically insured while travelling between locations.
The risk changes when the goods are moving.
For businesses importing goods into Kenya, this is particularly worth discussing with an insurance professional before the rainy season becomes more intense.
Does insurance cover El Niño damage?
This is probably the question many people will ask after searching for El Niño damages, flood damage in Kenya or El Niño insurance in Kenya.
The short answer is:
Insurance can cover certain losses associated with heavy rain, flooding or storms, but coverage depends on the specific insurance policy.
There is no single “El Niño insurance policy” that automatically covers every loss caused by the weather.
Instead, different types of insurance address different risks.
|
What could be damaged? |
Insurance to investigate |
What to check |
|
Your private car |
Comprehensive motor insurance |
Flood/storm cover, exclusions, excess and limits |
|
Motorcycle |
Comprehensive motorcycle insurance |
Own-damage cover and applicable exclusions |
|
House/building |
Home/property insurance |
Flood, storm and water-related risks |
|
Household belongings |
Contents/home insurance |
Contents sum insured and exclusions |
|
Business premises |
Commercial property insurance |
Property risks and insured values |
|
Business stock |
Stock/property cover |
Stock limits, location and exclusions |
|
Business income |
Business interruption cover |
Trigger events, indemnity period and limits |
|
Goods being transported |
Goods-in-transit/cargo insurance |
Transit risks, route and conditions |
|
Commercial vehicle |
Commercial motor insurance |
Own damage, use, flood/storm provisions and exclusions |
The important point is that the name of the insurance product is not enough.
Two policies can have different premiums because they provide different benefits, limits, exclusions, excesses and conditions.
That is why comparing insurance should mean comparing the protection not just the price.
Don't wait until your car is already underwater
This sounds obvious, but it is one of the most important things to understand about insurance.
Insurance is designed to protect you against future insured risks.
It is not something you normally buy after the loss has already happened.
If your car is already sitting in floodwater and you do not have the appropriate insurance, buying a policy afterwards does not turn the existing damage into an insured loss.
The same applies to a flooded shop, damaged stock or a house that has already suffered a loss.
So if the forecast has made you realise that you have a significant uninsured risk, review your cover before the damage happens.
What should you check before buying insurance for El Niño?
Don't just ask an agent:
“How much is the premium?”
Ask better questions.
1. What exactly is covered?
Ask whether the policy responds to the specific risk you are worried about.
For example:
“If my vehicle is damaged by flooding following heavy rainfall, is that loss covered under this policy?”
That's a much better question than simply asking whether the policy is “comprehensive”.
2. What is excluded?
Every insurance policy has exclusions.
Read them.
Pay particular attention to:
- Flood-related exclusions
- Storm-related exclusions
- Negligence
- Unauthorised use
- Maintenance-related damage
- Policy conditions
- Excesses
- Coverage limits
If you don't understand an exclusion, ask before buying.
3. Is your property adequately insured?
Imagine your house contents are worth KSh 3 million but you insure them for KSh 1 million.
You may have insurance, but you may still have a significant financial gap.
The same principle applies to:
- Vehicles
- Buildings
- Business stock
- Equipment
- Machinery
Make sure the insured value reflects the actual value you are trying to protect.
4. What is the excess?
An excess is the amount you may have to contribute toward a claim before the insurer pays the balance.
A policy with a lower premium may have different excess terms from another policy.
This is another reason why comparing only premiums can be misleading.
5. How do I make a claim?
Before you buy insurance, understand what happens after a loss.
Know:
- Who to contact
- How quickly you need to report the incident
- What documents you need
- Whether photographs are required
- Whether an assessment is required
- How repairs are authorised
- How the claim is eventually settled
Insurance is most valuable when you understand how it works before you need it.
How to prepare your car for heavy El Niño rains
Insurance should not be your only defence.
There are practical things you can do before the rains become severe.
Before driving
Check:
- Tyres
- Brakes
- Wipers
- Headlights
- Battery
- Windscreen
- General vehicle condition
When parking
Where possible:
- Avoid known flood-prone areas.
- Avoid parking near rivers or drainage channels.
- Look for higher ground.
- Do not assume that a parking area that was safe yesterday will remain safe during extreme rainfall.
When driving
Most importantly:
Do not drive through floodwater when you cannot determine its depth or whether the road underneath is safe.
A familiar road can become dangerous very quickly during heavy rain.
If a road is flooded, find a safer alternative rather than trying to prove that your car can make it through.
How to protect your home from heavy rain and flooding
A few hours of preparation can potentially save you a much larger headache later.
Before the rains intensify:
- Clean gutters and drainage channels.
- Check the roof for leaks.
- Inspect doors and windows.
- Clear blocked drains around the property.
- Move valuable electronics away from floors.
- Protect important documents.
- Raise vulnerable stock or equipment off the floor.
- Check outdoor drainage.
- Identify areas where water normally collects.
- Keep emergency contacts accessible.
And if you have insurance, keep your policy documents and insurer contacts somewhere you can access them quickly.
How businesses can prepare for El Niño
Business owners should think about both physical damage and interruption to operations.
Before the heavy rains:
Protect your stock
Move vulnerable goods away from the floor.
If your premises has flooded before, don't wait for the first rainfall to start moving inventory.
Protect your records
Back up:
- Accounting records
- Customer information
- Supplier information
- Invoices
- Contracts
- Important business documents
Review your insurance
Check:
- Building cover
- Contents
- Stock
- Equipment
- Business interruption
- Goods in transit
- Commercial motor insurance
Have a continuity plan
Ask yourself:
If my business cannot operate from this location for seven days, what happens?
Then ask:
What if it is 30 days?
That exercise alone can reveal risks that are easy to overlook when business is operating normally.
El Niño preparedness is not just about insurance
Insurance is important, but it is not a replacement for preparation.
You should still:
Clear the drainage.
Protect your stock.
Move valuable items away from flood-prone areas.
Avoid driving through dangerous floodwater.
Back up important documents.
Know where your family will go if your home becomes unsafe.
Check your insurance before you need to make a claim.
The goal is not to assume that something bad will happen.
It is to avoid being financially unprepared if it does.
So, should you get insurance because of El Niño?
The better question is not:
“Should I buy insurance because El Niño is coming?”
It is:
“If heavy rain or flooding damaged the things I own, could I comfortably absorb the financial loss myself?”
If the answer is no, it is worth reviewing your insurance.
A person with a KSh 1.5 million car faces a very different financial risk from someone with a KSh 200,000 car.
A small shop with KSh 100,000 of stock faces a different exposure from a wholesaler holding millions of shillings worth of inventory.
And a homeowner whose property is in a flood-prone area may have very different risks from someone living on higher ground.
Insurance should therefore be based on your actual exposure, not simply on the fact that there is an El Niño forecast.
Compare insurance before you need it
If the current weather outlook has made you realise that you may have an insurance gap, this is a good time to review your options.
GetCovered Kenya helps Kenyans compare available insurance options across different types of cover, including motor, home, business, travel, health, life and other insurance products.
The point of comparing insurance is not simply to find the cheapest premium.
It is to understand:
- What you are paying for
- What is covered
- What is excluded
- How much protection you have
- What excess applies
- Which insurer is providing the cover
- Whether the policy actually addresses the risk you are concerned about
Compare insurance options with GetCovered Kenya before the rains become a problem.
[CTA: Compare Insurance Quotes]
Frequently Asked Questions About El Niño Damage and Insurance in Kenya
What damage can El Niño cause in Kenya?
El Niño itself does not physically damage property. The concern is the weather conditions associated with it, particularly increased rainfall and the potential for flooding. These conditions can contribute to damage to vehicles, homes, business premises, stock, equipment, roads and goods in transit.
Does insurance cover El Niño damage in Kenya?
Insurance may cover certain losses resulting from flooding, storms or other weather-related events, depending on the type of insurance and the policy terms. Always check the specific policy's exclusions, limits and conditions.
Does comprehensive car insurance cover flood damage in Kenya?
It can. Comprehensive motor insurance may cover flood or storm damage to your vehicle, depending on the insurer and policy wording. Third-party motor insurance does not generally provide cover for damage to your own vehicle.
Does third-party car insurance cover flood damage?
Third-party motor insurance primarily covers specified liabilities to other people. It does not generally cover damage to your own vehicle caused by flooding.
Can I buy insurance after my car has been damaged by flooding?
Insurance is intended to cover future insured risks. You should not expect to purchase insurance after an incident has already occurred and then claim for that existing damage.
Does home insurance cover flooding in Kenya?
It depends on the policy. Ask the insurer specifically whether flooding, storm damage and related water damage are covered and what exclusions or limits apply.
What insurance covers business stock damaged by flooding?
Depending on the business and policy structure, commercial property or stock insurance may provide protection against specified insured risks. The policy wording determines whether a particular flood-related loss is covered.
Can business interruption insurance help after flooding?
Business interruption insurance can provide cover for certain financial losses arising from interruption of business following an insured event, subject to the policy's triggers, limits, exclusions and indemnity period.
Does insurance cover goods damaged by floods while being transported?
Goods-in-transit or cargo insurance may cover specified losses while goods are being transported. The applicable policy, route, mode of transport and exclusions determine what is covered.
Where can I compare insurance quotes in Kenya?
GetCovered Kenya allows consumers to explore and compare insurance options from insurers operating in Kenya. You can compare available covers, premiums and policy details before choosing a policy.
Final thought: Don't wait for the water to reach your doorstep
Nobody knows exactly what the next few months will look like for every part of Kenya.
A seasonal forecast is not a guarantee that your neighbourhood will flood.
But you don't need a guarantee of disaster to take sensible precautions.
If you drive a car, own a home, operate a business, hold valuable stock or regularly move goods around the country, take a few minutes to think about what heavy rainfall could mean for you financially.
Check your drainage.
Protect your property.
Prepare for the rains.
And most importantly, know what your insurance actually covers before you need it.
Because when the water is already inside the house, the shop or the car, it is too late to start asking what your policy says.
Compare your insurance options with GetCovered Kenya and make sure the cover you have matches the risks you actually face.